



The New Institutional Horizon: Highlights from CV Summit 2026
The question facing finance is no longer whether AI and digital assets will matter, but how quickly the industry can rebuild around them. At CV Summit 2026, that question shaped almost every conversation.
On 29 and 30 September, CV Summit 2026, hosted by CV VC and CV Labs, and presented by Franklin Templeton, brought banks, asset managers, founders, technology companies and investors into the same room to discuss where digital assets and AI are heading next. Global leaders such as BlackRock, UBS, Deutsche Bank, Visa, Google, and Binance shared the program with leading Swiss institutions, including PostFinance, SIX, Sygnum, SCRYPT, Luzerner Kantonalbank, G-20, TWINT, alongside frontier technology players including Ripple, Cardano and Stellar.

Mathias Ruch, Founder and CEO of CV VC, set the tone of CV Summit 2026 in the opening keynote, presenting facts that demonstrated the convergence of AI and digital assets, with the institutional space. He outlined that what used to be three stories running in parallel has evolved into one story. Agents that transact need digital money, such as stablecoins that can’t wait for a human click. At the same time, humans need to trust and hence trust in stablecoins is getting built right now by institutions.
Over the two days that followed, that convergence ran through almost every session on the Anchor, Catalyst, and Deep Dive stages, spilling over onto the exhibition floor and into the networking across the conference. Here’s what was discussed, and what it tells us about where digital assets and AI are heading next.
Financial Infrastructure Built for Agents That Never Sleep
Much of today’s financial infrastructure was designed around human working hours, and the arrival of AI agents highlights the efficiency and economic benefit of systems that can trade and manage money 24/7. Franklin Templeton’s Christopher Perkins framed the shift from the market's side. In their natural state, he argued, markets run around the clock, and trading hours and weekend closures are barriers built around human work cycles. Those barriers also carry a cost: because markets can close, institutions must hold more collateral to cover the days they cannot trade.

Christopher Perkins sees regulatory clarity, particularly in the United States, as the turning point. With regulators now out in front, institutions can engage with digital assets without the regulatory risk that held them back, and every institution he speaks to, now has a dedicated digital-asset team. In his view, the industry is moving towards fundamentals and utility, and institutions now carry more risk by staying out of digital assets than by engaging with them.
Christian Moser, Head of New Business at TWINT, made a similar case from the payments side: “We build our financial system for humans, but humans need to sleep.” Batch clearing and opening bells were once a form of control. As agents begin to act and transact on their own, that friction becomes the system’s biggest limitation.
Christian Moser gave a practical example: if CHF 50 million lands in a company’s account at 3 am, a treasury agent could invest the excess cash and hedge currency risk before the CFO wakes up. Because agents cannot show a passport, they need machine identities and digital money such as stablecoins. To manage the risks, he suggested setting clear rules for automated systems, keeping humans in charge of oversight rather than approving every individual transaction.

The Agentic Finance Report, launched live on the Anchor Stage, set out what a financial system built for agents will need. Marcus Maute of TensorX, who presented the report, sees the timing as no accident: stablecoins have become “the new normal”, and tokenized assets are scaling just as AI models have become capable enough to act on them. He summed up where this is heading: “The next human job is defining the mandate.”
BlackRock’s Dr. Dirk Klee, who called this convergence bigger than the ETF revolution he helped pioneer, made the connection explicit: AI can decide what to do, but as it incorporates moving money and settling trades, the current system is restricted by the time during which it can complete the actions. For the industry, this is the clearest link between the two technologies: AI supplies the decisions, and digital assets supply the rails that let those decisions be carried out at any hour.
Tokenization Gets Practical

Dr. Alexander Thoma, Head of Digital Assets at PostFinance, was candid about tokenization's early phase: “We treated tokenization as a solution looking for a problem.” Clients wanted their normal banking interface, and progress only came once tokenization moved behind the scenes into payments and settlement between banks.
The topic of collateral was visited throughout the Summit. Christopher Perkins described tokenization as the next step in the electronification of markets, pointing to Franklin Templeton’s Benji platform, where holders continue to earn yield until the moment of transfer, and fund shares can be posted as collateral.
Patrick Loepfe, Co-Founder and Chairman of GenTwo, called collateral management “the biggest use case”. When he started out as a derivatives trader 25 years ago, OTC collateral was a paperwork nightmare. Today, in his words, “it’s the same nightmare.” Collateral promised to several counterparties at once has fed past financial crises, and on-chain collateral that is transparent and settles atomically could close that gap.
Demand remains the open question. On the Catalyst Stage, Niklas Kunkel, Founder and CEO of Chronicle, noted that the biggest holders of tokenized assets today are not institutions or retail investors: “It’s actually the DeFi protocols themselves.” The next test is whether institutions will want the on-chain version of an asset they can already hold through their bank.
Stablecoins and the New Plumbing
Stablecoins have moved well beyond crypto trading into payments and settlement, and the banking sector is now responding. Dr. Alexander Thoma was just as direct on payments, arguing that stablecoins offer a better cross-border experience than banks do today and have acted as “a wake-up call” to the industry. He pointed to the Swiss deposit token project and the BIS’s Project Agorá as the banking sector’s response, and urged regulators to “legislate at speed”. His message to the industry was short: “No more proofs-of-concept.”
For institutional clients, settlement speed has become the first question. “The number one problem is the settlement,” said Gabriel Titopoulos, Managing Director, Markets & Trading at SCRYPT. “Above an hour doesn’t work.” He outlined that the institutional demand for speed can no longer be met by today’s settlement cycles. T+2, T+1, and even same-day settlements are already falling short. Stablecoins can close that gap, but only if the cash side of a trade moves just as fast, which makes liquidity, rather than the technology itself, the real deciding factor.
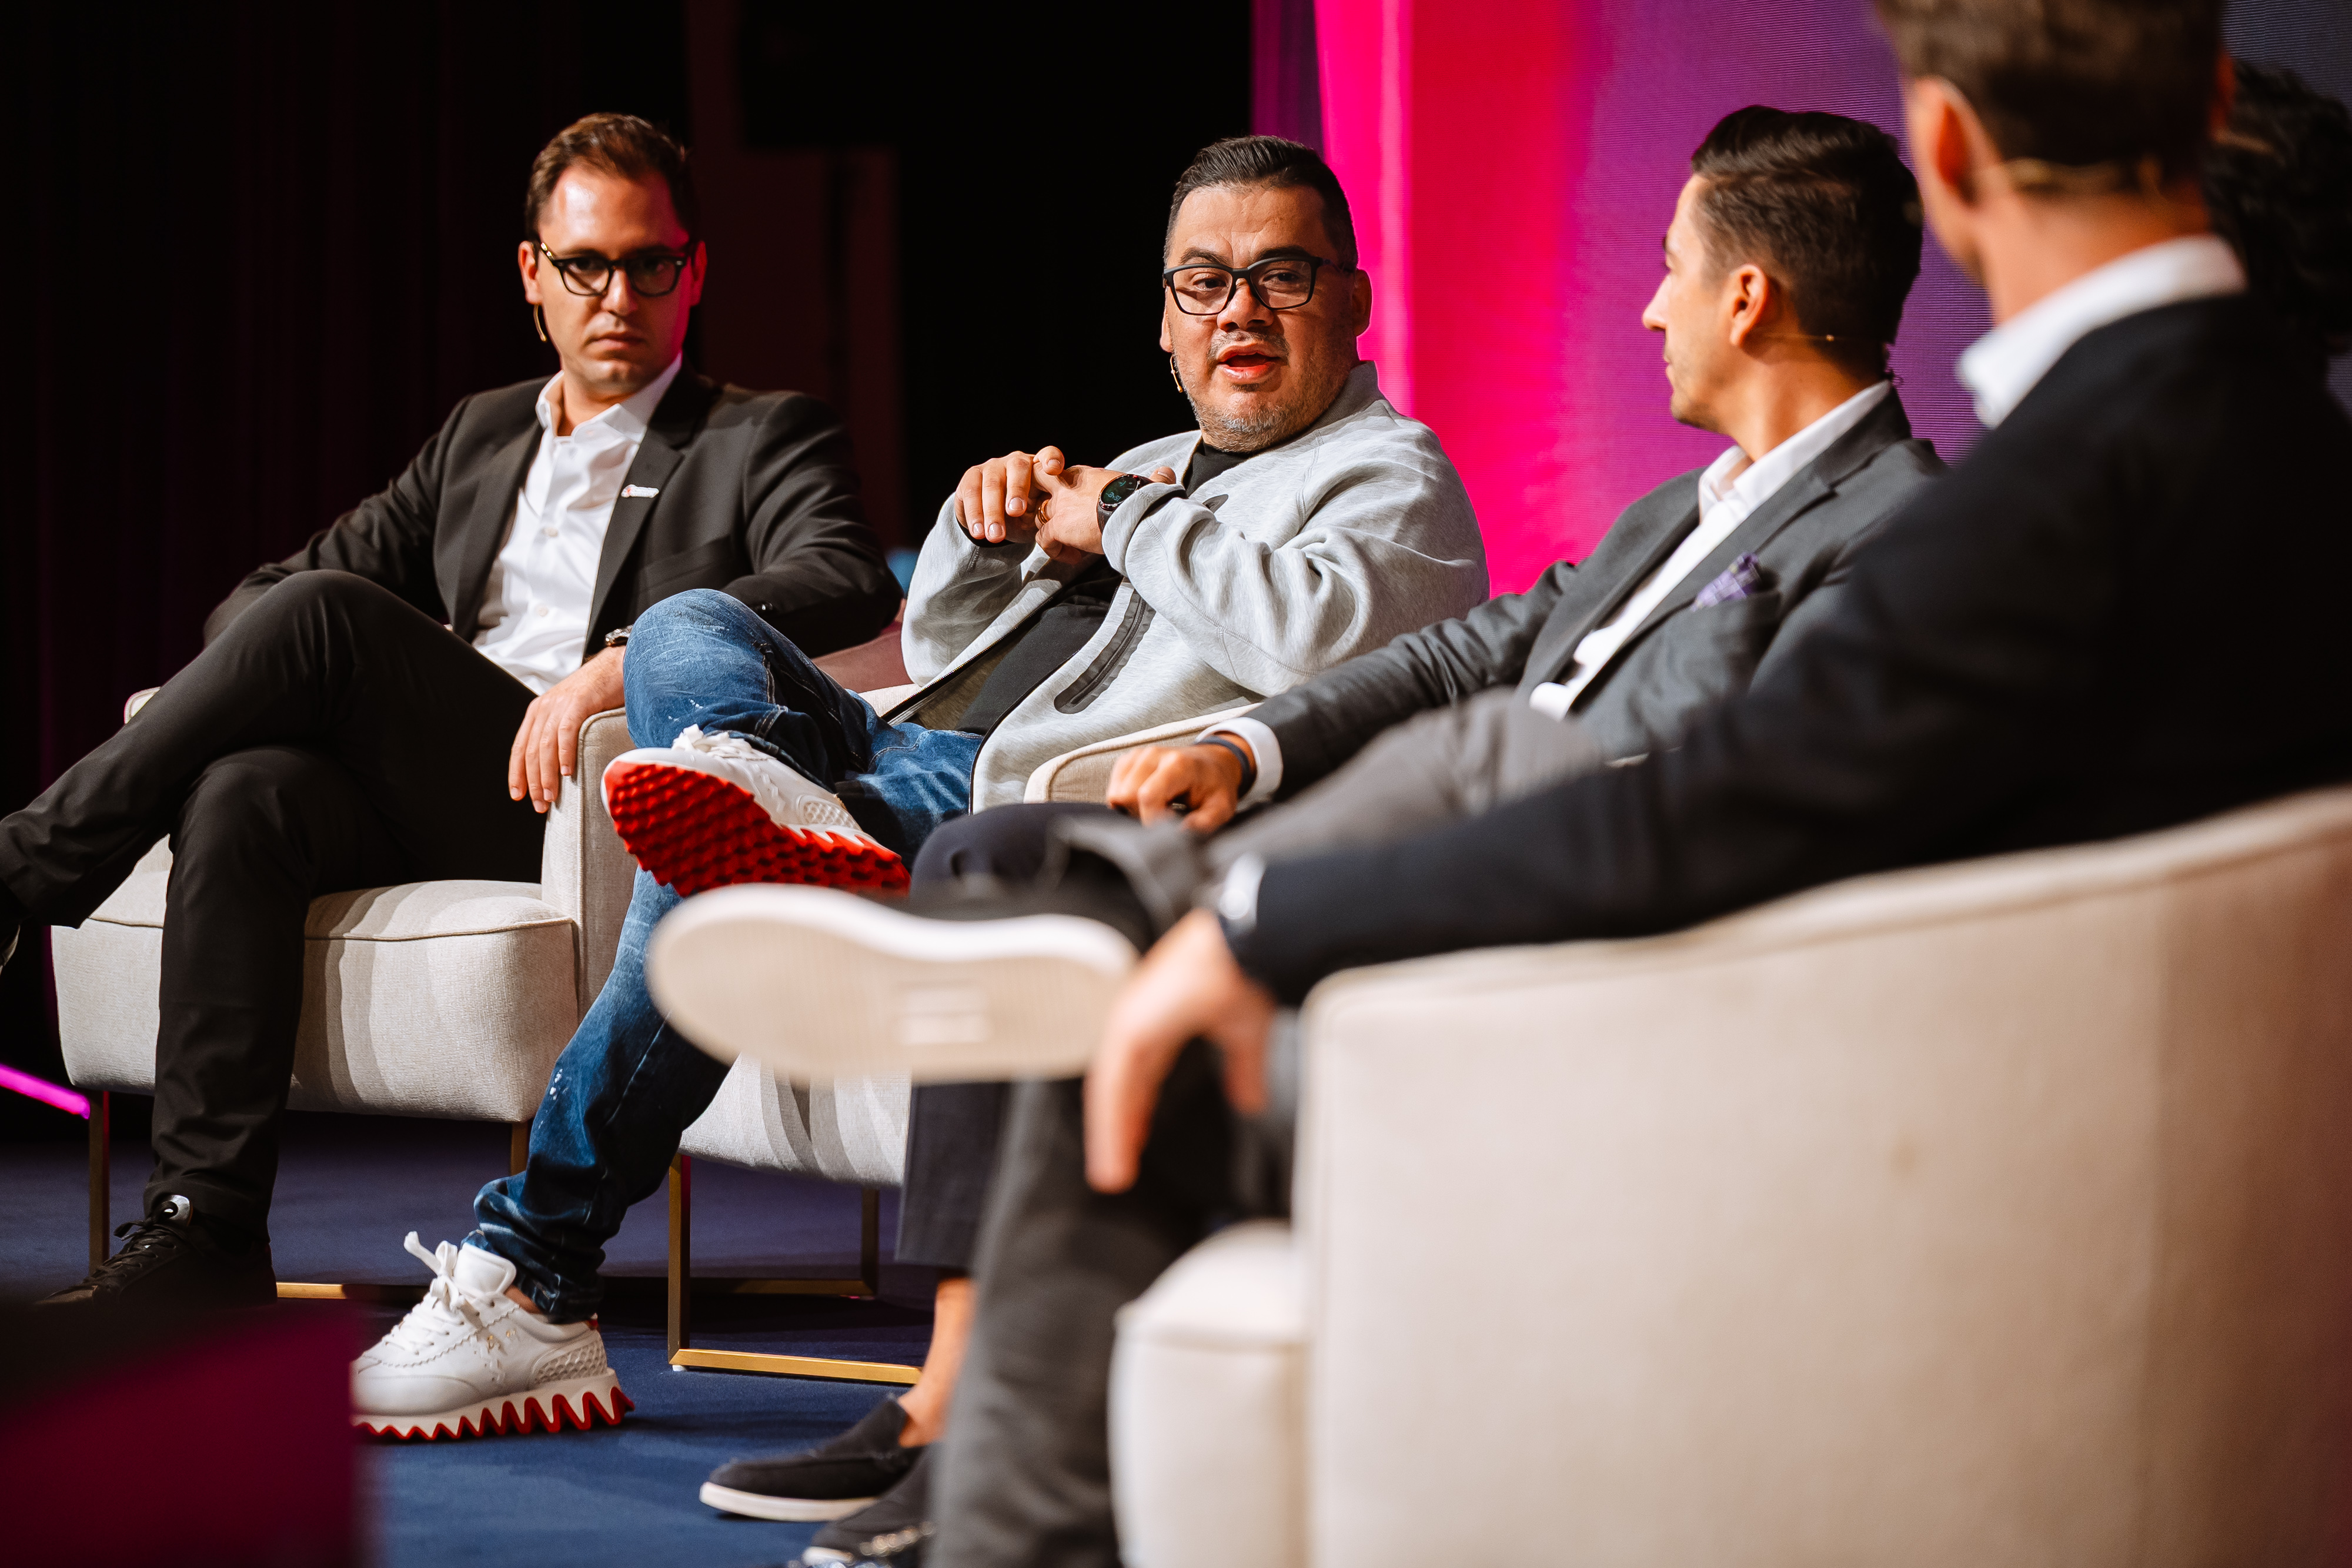
Oscar Flores, CEO and Co-Founder of Unblock, expects the technology to fade from view: “Probably ten years from now, everybody’s going to be using stablecoins without knowing it.” Nobody at an ATM thinks about how it settles with Mastercard, he pointed out, and stablecoins will be the same.
Banks, meanwhile, are still defining their role. Deutsche Bank’s Manuel Klein described tokenized deposits and stablecoins as very different instruments: one stays within a bank’s own client base, while the other is a bearer instrument that competes directly with correspondent banking. Distribution, he said, is the hardest problem stablecoins face.
UBS’s Jaya Bhatia looked at the client side, proposing that banks don’t need to become crypto-native to serve fast-growing digital-asset founders, but they do need to become crypto-literate, and to bank the person behind the company rather than just the crypto. Whether through stablecoins or tokenized deposits, money is moving on-chain. The competition now is over who distributes it, and which institutions clients trust to hold it.

From AI Pilots to Real Returns
The most-cited figure from the AI sessions came from a widely shared MIT study: around 95% of corporate AI pilots show no real financial impact. Across both stages, speakers agreed that the problem is rarely the technology itself. Yuval Dvir of SandboxAQ argued that today’s models, open-source ones included, can already handle around 90% of industry workloads, so the real advantage now lies in proprietary data, distribution, and specialist knowledge. Summing up the discussion on AI adoption at scale, _Futureshift’s Sarah Maria Röthlisberger put it simply: “AI is the easy part. Scaling is a people job, and it starts with leaders who go first.”
A common thread across the AI sessions was that most organizations automate old processes instead of redesigning them. “People are still trying to create faster horses,” said Alex Dean of Unit8. Banks have used AI for more than a decade, he noted, so the challenge now is adapting to a new wave of capability.
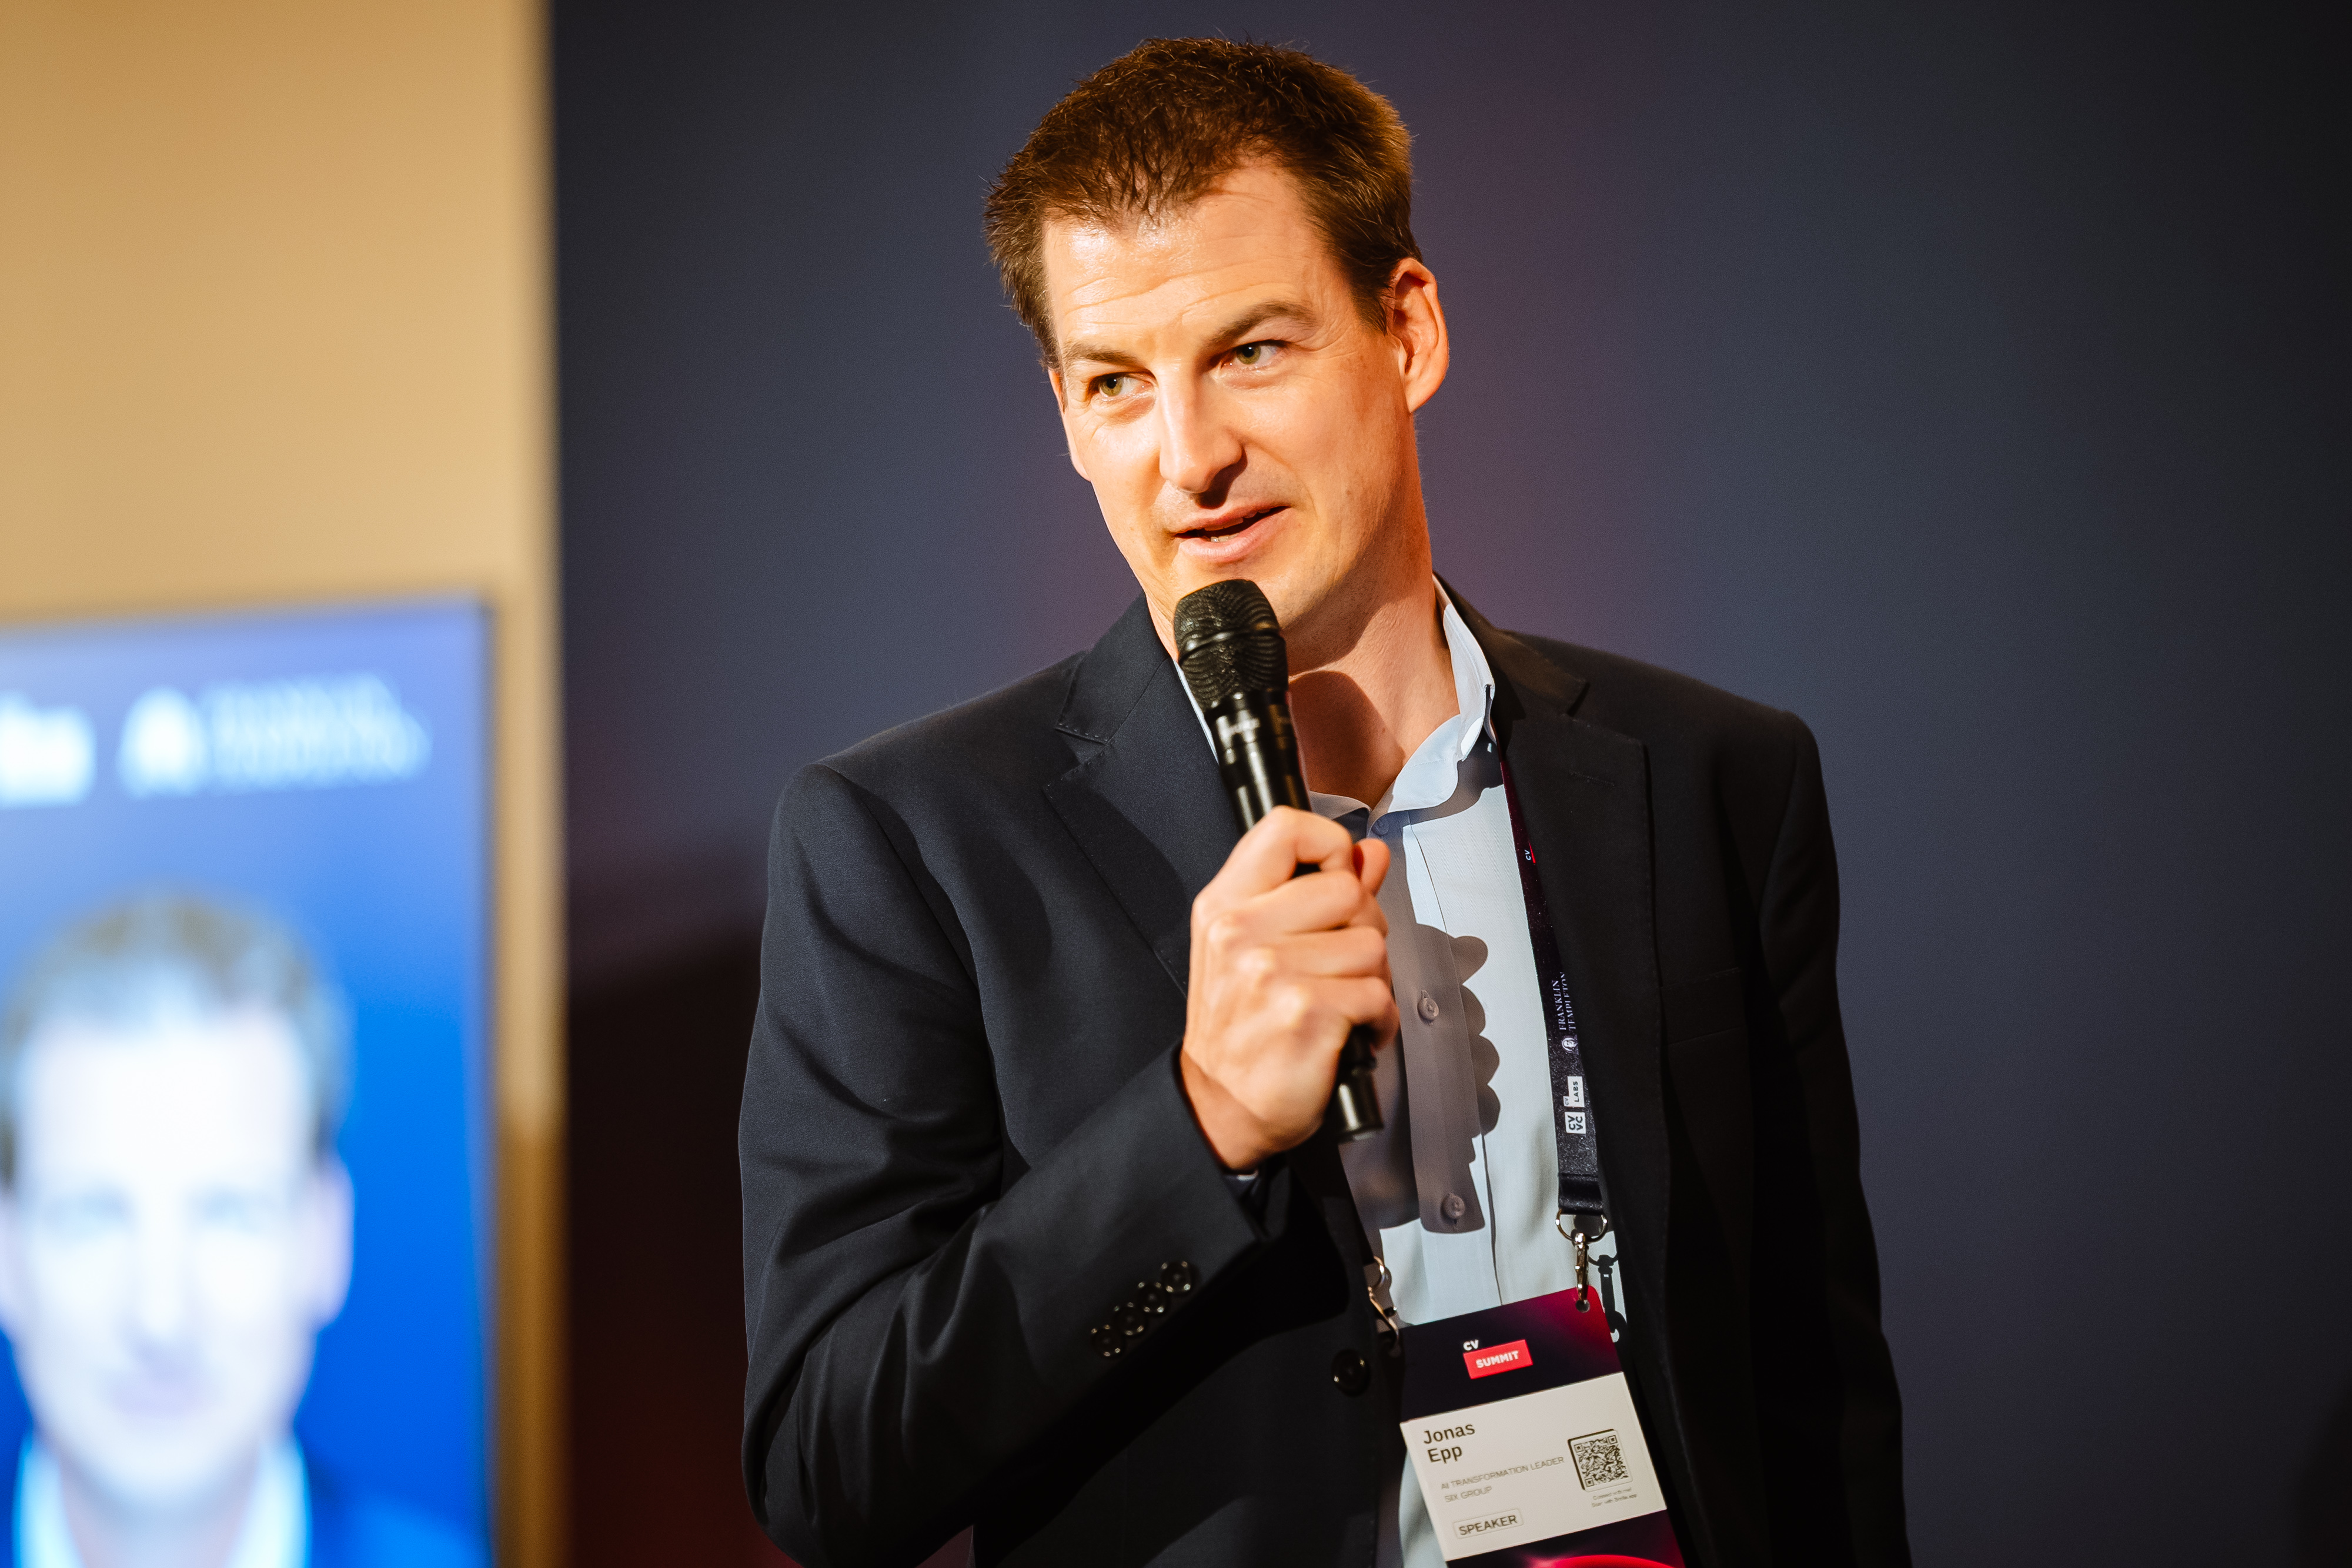
Jonas Epp, AI Transformation Leader at SIX, proposed a better test of adoption than license counts: how much has your working day actually changed? Too many firms, he argued, still treat AI as an IT rollout and judge it on old cost-saving metrics, rather than on productivity and the speed of decision-making. For financial institutions more broadly, that means moving at two speeds: quickly for employees using AI day to day, and far more carefully for the agents running behind the scenes in critical systems, where failure is not an option.
Franco Mignemi, CEO of Ephelia Group, observed that many banks have been focused more on building new policies and procedures than on adopting AI. His own firm made AI certifications mandatory for every employee, so that no part of the team is left behind. For the wider industry, that shifts the race in AI from access to models towards organizational change, and the firms that redesign how work gets done will be the ones that see the returns.
That redesign goes beyond workflows. On the Catalyst Stage, Julius Baer’s Sarah Gadd argued that culture is the next frontier of AI adoption. In her view, culture is how a firm makes decisions in the grey areas its rules don’t cover. As agents become a firm’s main interface with its clients, they will effectively become that culture. Firms will need to turn their principles into clear instructions for agents and let those agents earn autonomy over time, much like a new hire. Leaders, therefore, need to decide how they want AI to behave when no one is watching.

Trust by Architecture
As agents move from pilots into real financial workflows, accountability is becoming one of the defining questions for both AI and digital assets. Who answers for an agent’s actions? Christoph Makni of Migros Bank, speaking in a personal capacity, rejected rubber-stamp oversight: “We don’t talk about humans in the loop, we talk about humans in control.”
People asked to approve every AI output will soon stop checking properly, he warned. In his model, every agent runs inside deterministic workflows with a kill switch and has a human owner who is fully accountable. As agents take on work that touches client money, more institutions are likely to follow a similar approach.
The law points in the same direction. As Michael Kunz of MME pointed out: “You can’t sue the agent.” Product liability can’t be contracted away, and when a seller doesn’t know it is dealing with an agent, the purchase is likely to bind the person or firm behind it. Dr. Petar Tsankov of LatticeFlow AI added that he has seen “almost zero vendors that would absorb any kind of liability if the system misbehaved”. For now, the risk sits with whoever deploys the agent, so banks and asset managers need their own layers of control rather than relying on the AI provider.

Regulation is still catching up. In the case of Switzerland, there is no AI-specific law yet, and FINMA treats AI as an operational risk like any other, which leaves the boundaries largely to each institution. Lena Götzinger of Zürcher Kantonalbank reframed a question accordingly: “The question you need to ask is not, is AI allowed? The question is, is this specific AI use case in line with our risk appetite?” It is a pragmatic approach that puts the responsibility on firms to define their own guardrails and monitor them continuously.
This is also where AI and blockchain start to reinforce each other. Frederik Gregaard, CEO of the Cardano Foundation, wants trust built into the infrastructure itself, moving from “trust but verify” to “trust by architecture”. Stablecoin micropayments, he explained, can cap what an AI agent is able to spend and leave an audit log of every action, while verified identity data from banks and registries anchors who stands behind it. The result could be continuous, affordable audits in place of a spot check every twelve months, and a practical answer to the accountability gap that agents create.
Building trust into the infrastructure also means securing it, and with instant, final settlement, there is little room to recover from mistakes, or as Halborn’s Jacques Boschung put it: “Finality is raising the stakes.” Halborn’s research shows that most recent incidents stem from off-chain weaknesses such as social engineering and poor key management, rather than flaws in the code itself. With digital assets, he said, institutions are now securing “the value itself”, so security can no longer sit apart from risk management. For an industry moving towards 24/7, agent-driven markets, trust will increasingly be engineered into the system rather than assumed.
Switzerland, Europe, and the Global Stage
Switzerland was early to digital assets, with its DLT law in force since 2021 and various banks now offering digital-asset access to their clients. The question at CV Summit was whether it can keep that lead as other markets move faster.
Philipp Rickenbacher, Chairman of CV VC, opened Day 2 with a challenge to incumbents. Disruption rarely arrives as a big bang; it builds until technology outruns the organizations using it. If a few of the largest US banks launched 24/7 markets for tokenized securities, Swiss banks could not afford to wait five years to respond. Switzerland, he said, has to “run, not walk”, and incumbents should use the trust and capital they already hold to “actually create the future in which we want to live.”
The same urgency applies to AI. Zurich is home to one of Europe’s most dynamic AI ecosystems, anchored by ETH Zurich and Apertus, Switzerland’s fully open language mode. Daniel Naeff of the ETH AI Center framed sovereignty as resilience rather than self-sufficiency:
“Sovereignty is much more about resilience, about having options.” Europe’s edge, he argued, lies in the proprietary data held inside its companies, while Dr. Daniel Dobos of the AI for Good Impact Initiative expects open models to win in the long run. At ETH Zurich’s Agentic Systems Lab, Dr. Robert Jakob showed what that talent looks like in practice, with students working alongside coding agents that act like “a professor advising you 24/7”.
The view also reached well beyond Europe. Ahmed Bin Sulayem, Executive Chairman and CEO of DMCC, described Switzerland and Dubai as complementary hubs: “Zurich and Dubai do not need to become the same thing. Their value lies precisely in being different.” For Switzerland, the opportunity is to remain the place where digital innovation earns institutional trust, while staying connected to the faster-moving markets around it.
Looking Beyond 2026
Over two days, CV Summit 2026 brought together more than 200 speakers across 70+ sessions, with 60+ partners and more than 150 institutions in the room.
A few years ago, conversations at events like this one centered on whether blockchain and AI would ever find a place in mainstream finance. This year’s discussions showed how far the industry has moved since then. Banks and asset managers are no longer asking whether to engage. Instead, they are working out how to settle, collateralize, and serve clients on new technology rails, and how to bring AI into the core of their operations rather than the edges.
The next phase will be shaped by continuing convergence. As AI agents begin to transact on their own, they will need programmable money, always-on markets and infrastructure where trust is built in from the start. That makes digital assets less a separate sector and more the foundation an agent-driven economy will run on. CV Summit 2026 brought together the people building that foundation, and the most telling sign of progress may be how ordinary much of it already sounded.
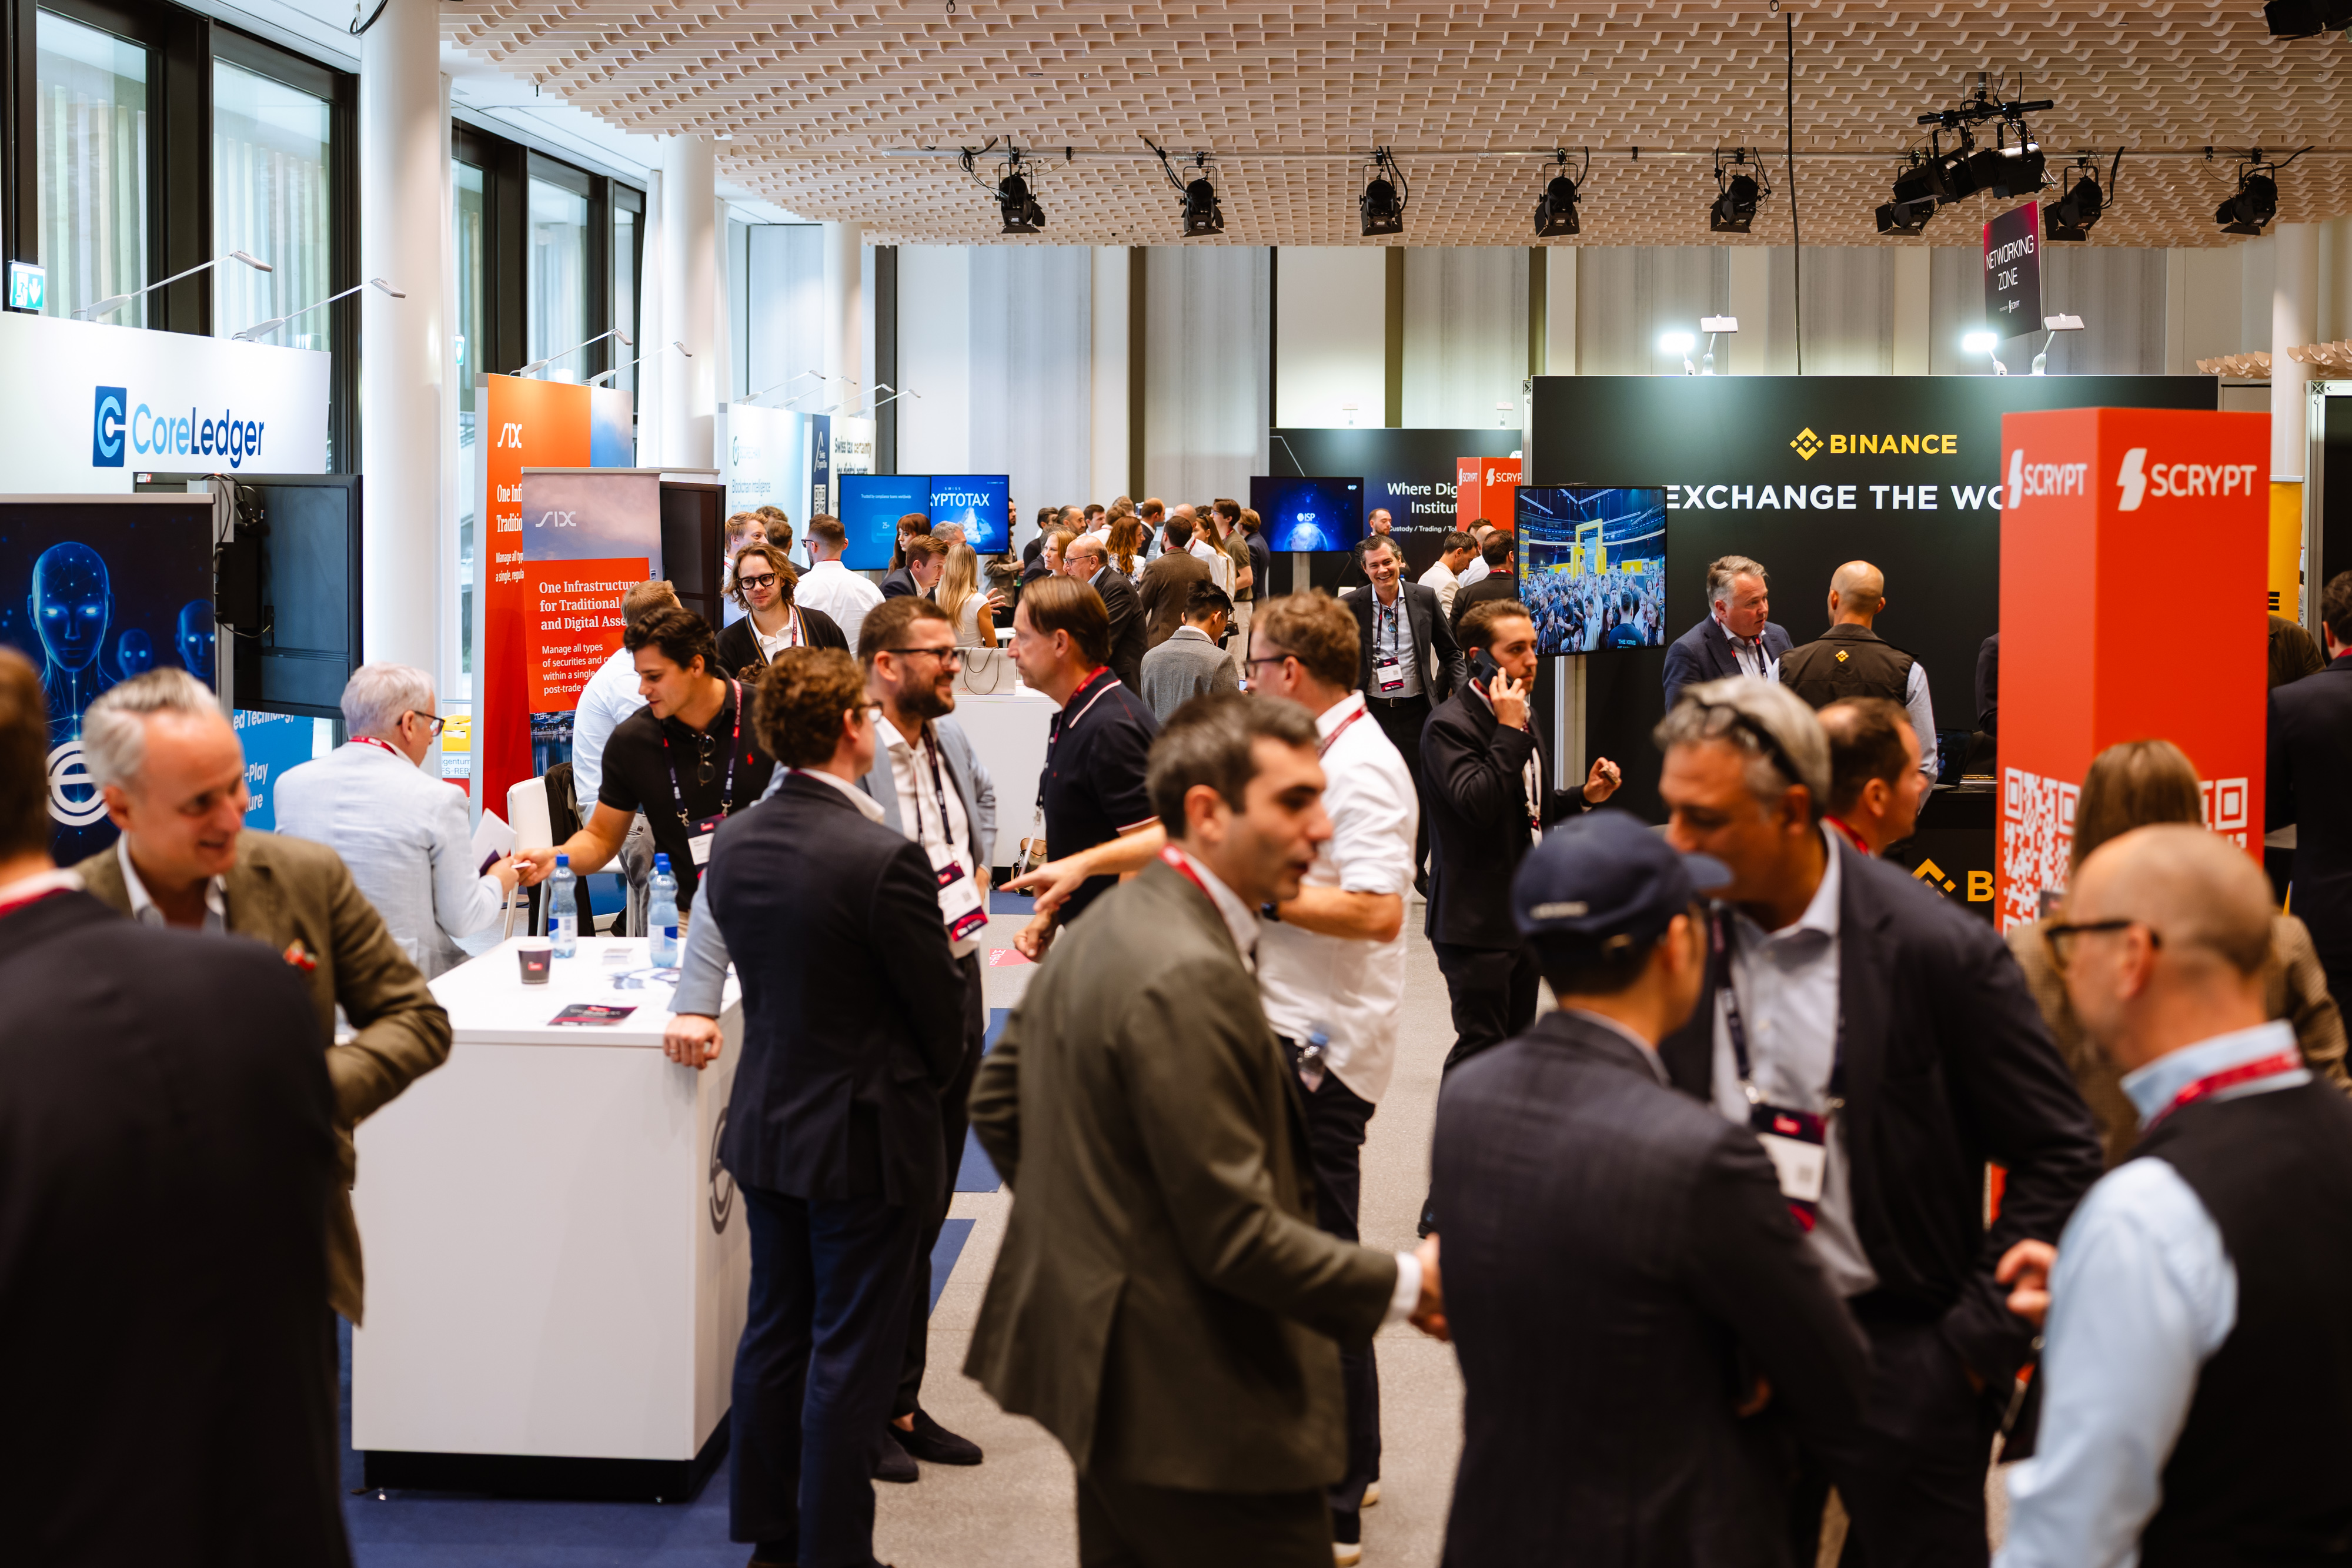
Much of CV Summit’s value was created between sessions. Over 1,400 meetings were scheduled through the networking app powered by SCRYPT, turning conversations into concrete next steps. On the evening of Day 2, the CV VC Boat Cruise on Lake Zurich gave speakers, partners and guests the chance to continue those discussions in a more relaxed setting, as the Summit closed with a view of the city it calls home.
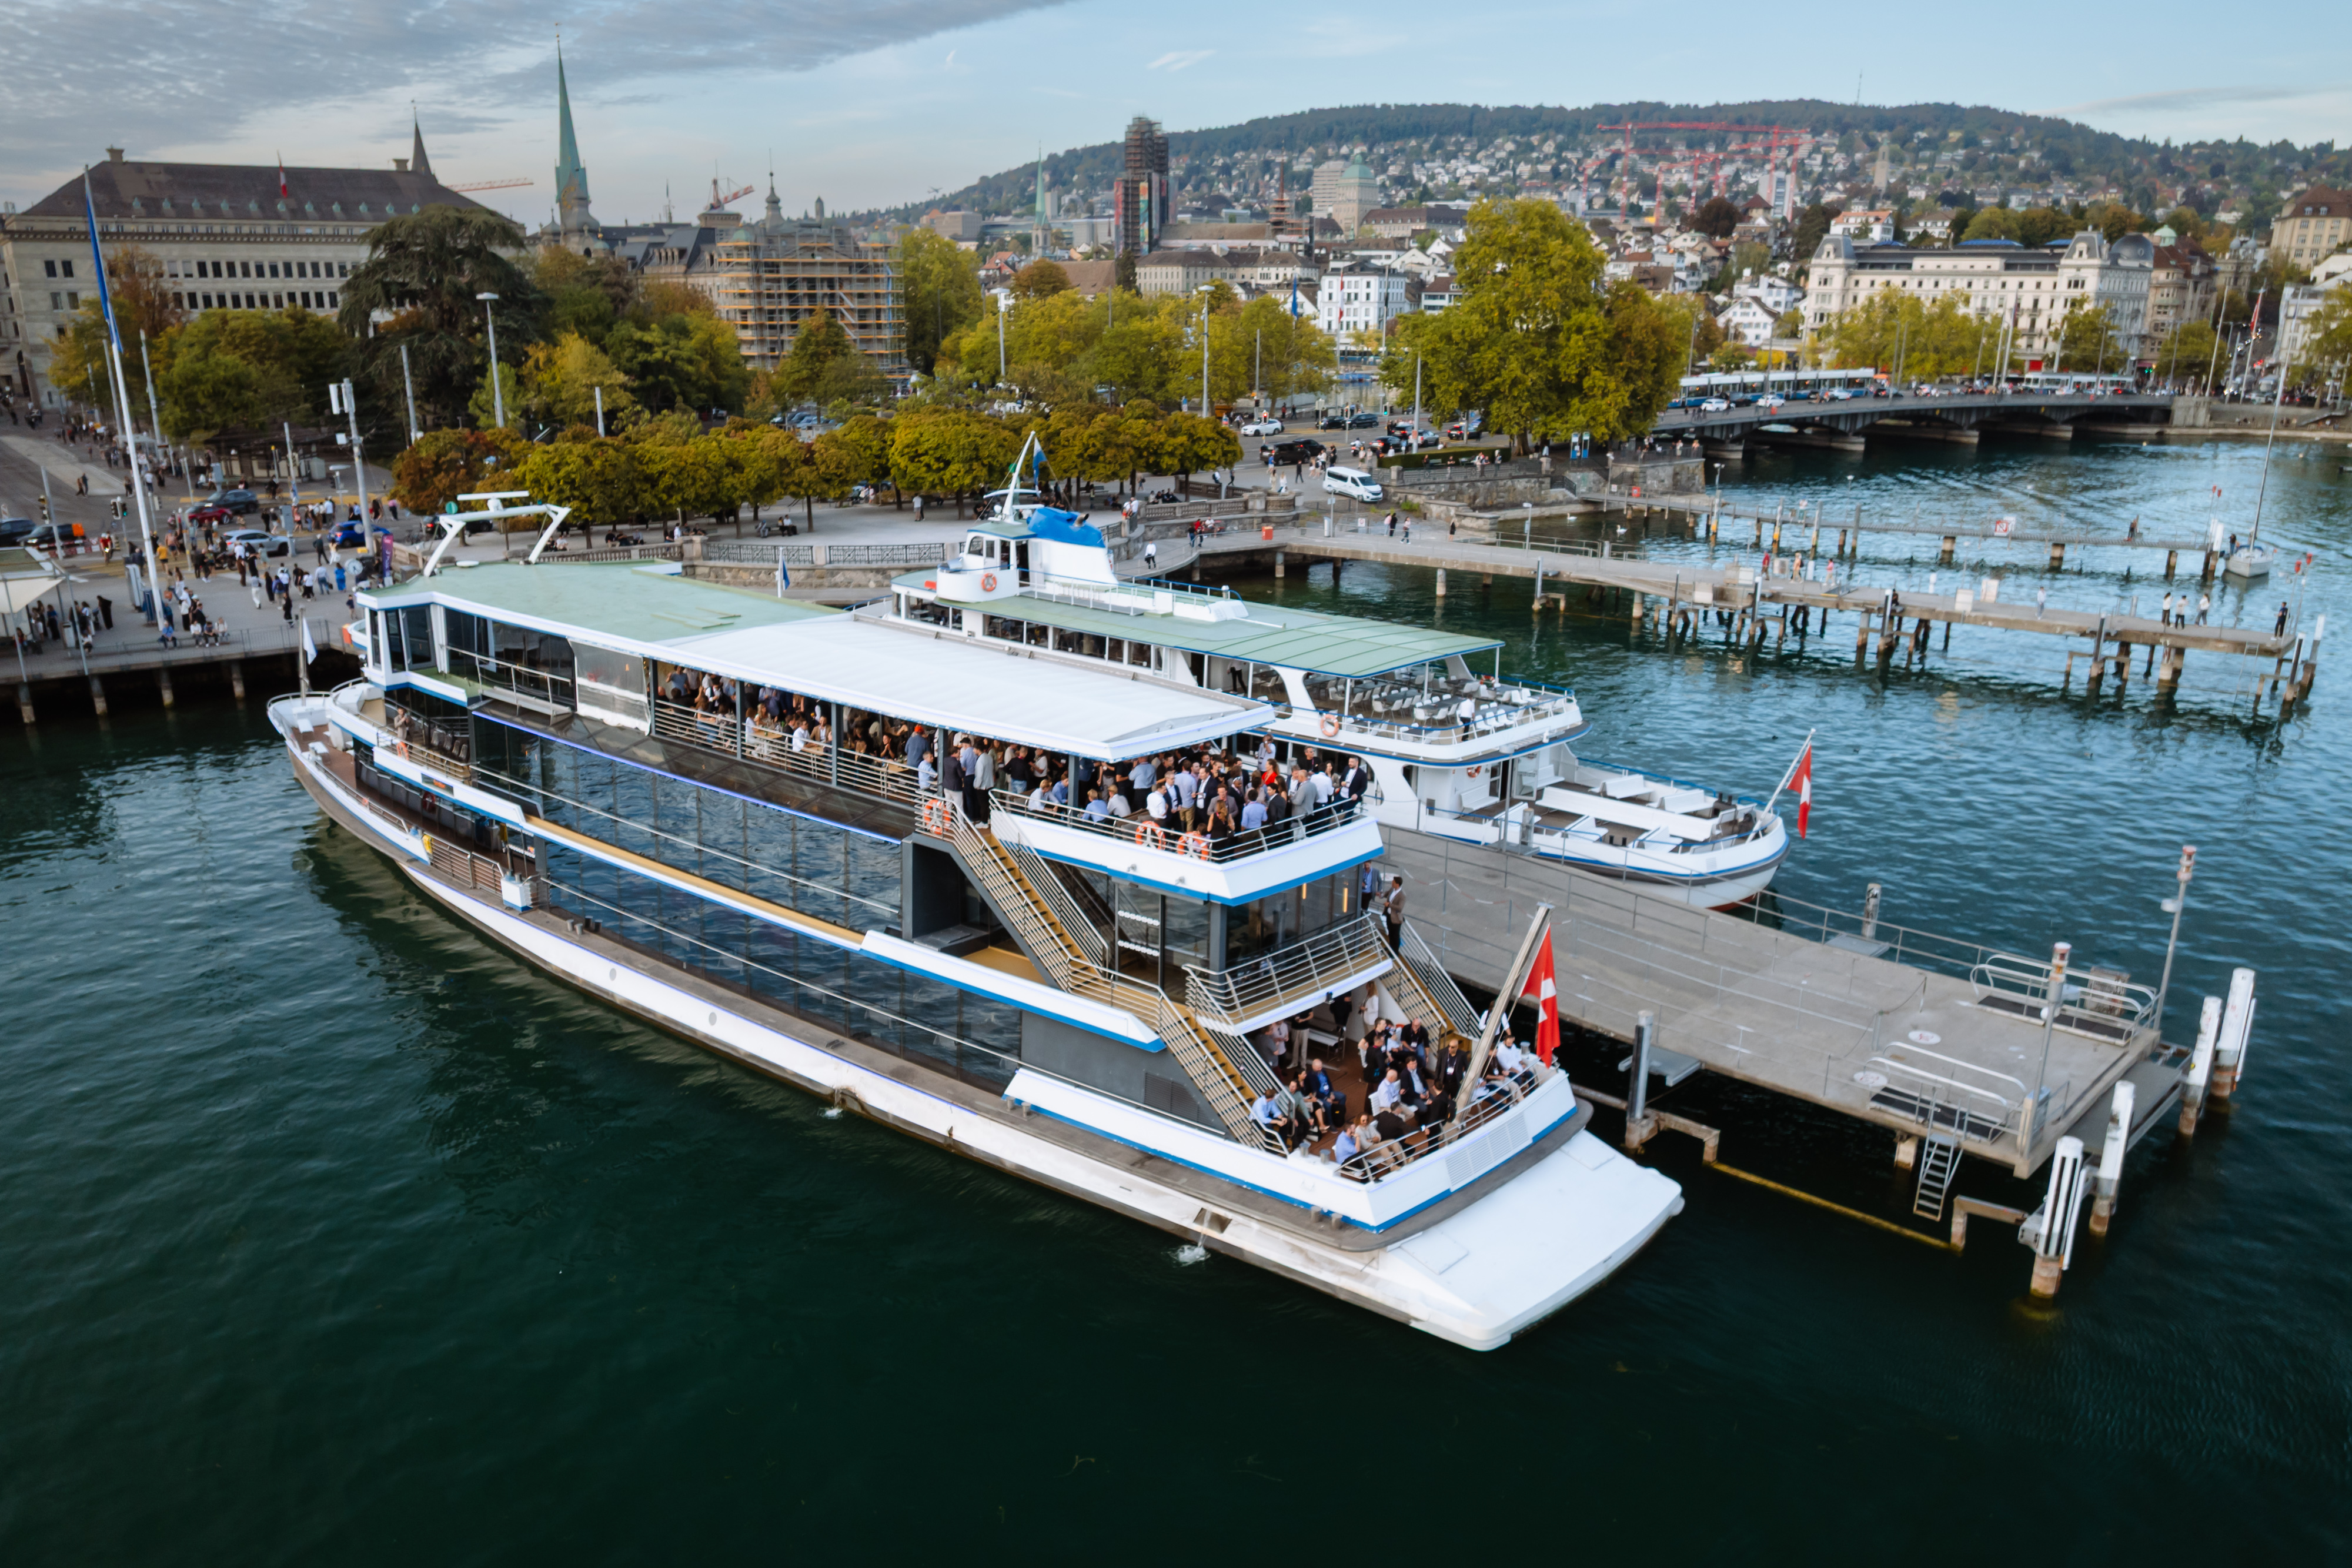
Our thanks go to presenting partner Franklin Templeton, to every partner and speaker, and to everyone who joined us in Zurich. CV Summit 2026 brought together institutions, builders and investors from across borders, and the conversations that started here have already set the agenda for 2027!


